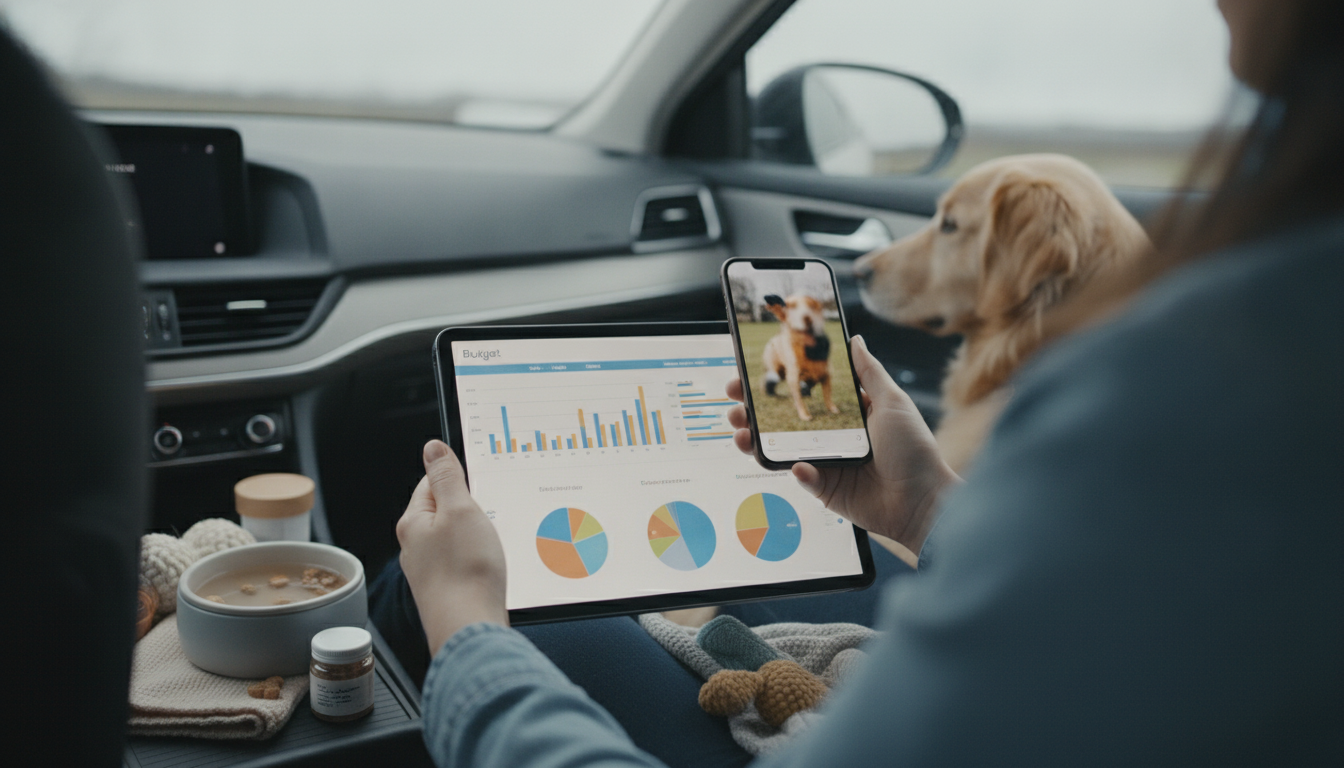
Start by treating pet care like a monthly bill with a built-in cushion for surprises. A practical budget includes routine needs (food, grooming, preventatives) and a separate plan for irregular costs like annual exams, vaccines, and emergencies. The goal is to avoid “big vet bill panic” by spreading costs across the year.
Write down what you reliably spend every month: food, treats, litter or waste bags, grooming basics, training apps/classes, and parasite prevention. If you buy in bulk or seasonally, average those purchases across 12 months so your budget reflects the true monthly cost.
Many of the biggest pet expenses don’t happen monthly—think wellness visits, vaccines, dental cleanings, and licensing. Estimate what those typically cost in your area, then divide by 12 and set that amount aside each month. This keeps “once-a-year” bills from derailing your finances.
Unexpected injuries and illness are the hardest part to plan for, so separate your emergency savings from your routine pet budget. Set an initial target you can reach quickly (even $300–$500 helps), then grow it over time. Keep it accessible (like a high-yield savings account) so you’re not relying on high-interest credit.
Budgeting is easier when you know what’s coming. Use a calendar or reminder system for medication refills, annual checkups, and preventatives, then “pre-fund” those dates with your monthly set-asides. For a detailed checklist of common dog costs, due dates, and ways to plan a vet fund, see this guide to budgeting for dog expenses.
Pets’ needs change with age, health, and lifestyle. Revisit your numbers quarterly and after any vet visit—then raise or lower your monthly set-asides so your budget stays realistic.
A solid starter goal is $300–$500, then build toward one to three months of your typical pet-related spending. Increase the fund faster if your pet is older, has chronic conditions, or is prone to accidents.

Leave a comment
You must be logged in to post a comment.