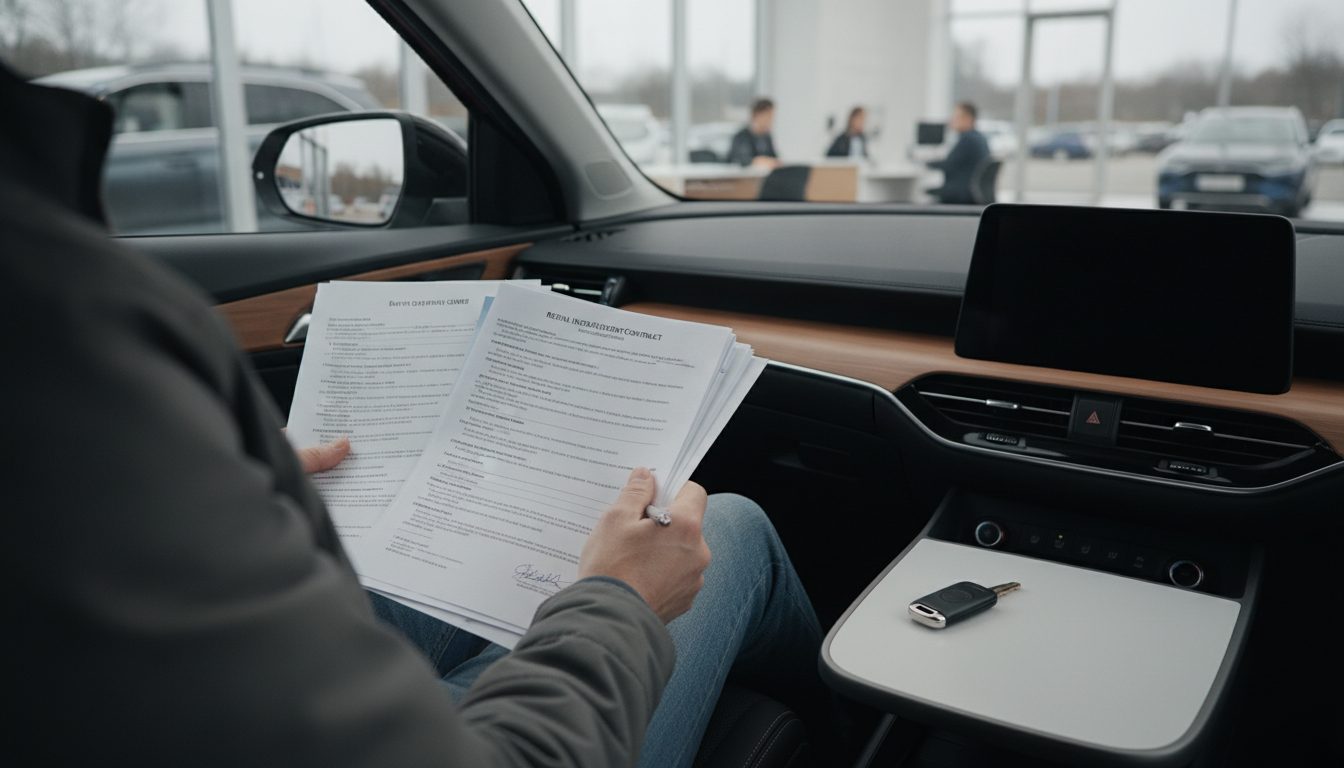
Before signing a car loan agreement, read every document that controls your interest rate, total cost, and your obligations if something goes wrong. Dealers and lenders often present paperwork in a stack, but a few specific forms do most of the “fine print” work. Taking time to review them can prevent surprises like higher APR, unexpected fees, or add-ons you didn’t intend to buy.
This is the core document. Confirm the APR, amount financed, total of payments, payment schedule, and whether the rate is fixed or variable. Check for prepayment penalties, late fees, and any clauses that allow the lender to change terms under certain conditions. Make sure the “cash price,” “down payment,” and “trade-in” numbers match what you agreed to.
This disclosure breaks down the finance charge, APR, amount financed, and total payments in a standardized format. Use it to compare the real cost of financing and to spot discrepancies between what was quoted and what’s being signed.
Ask for an itemization of every fee and product. Look for document fees, acquisition fees, gap insurance, service contracts, wheel/tire protection, paint or fabric protection, theft-deterrent packages, and “etching.” If you don’t want an add-on, get it removed and have the totals reprinted.
The buyer’s order typically summarizes price, taxes, registration, and extras. The odometer statement is required for most sales and should match the vehicle’s mileage. Any mismatch should be resolved before signing.
If you’re taking the car home before financing is finalized, read the conditional delivery terms carefully. Understand what happens if the lender rejects the deal or changes the rate—especially whether you must return the car or renegotiate.
For a deeper breakdown of APR, fees, and common add-ons to watch for, review the full guide here: https://elevatdlife.com/guide-car-financing-fine-print-apr-fees-add-ons-explained/.
Often, yes—many add-ons are optional. Ask for an itemized list, decline what you don’t want, and request updated paperwork showing the revised total before you sign.

Leave a comment
You must be logged in to post a comment.